Home services  /  HVAC
Sell-side advisory for HVAC owners

Selling an HVAC company.

Maintenance agreements, technician depth and how much still runs through you. How a buyer reads an HVAC company, and what to put in place before one does.

The HVAC market, in numbers

Ninety-two HVAC deals in seven months.

Buyers are active, well capitalized and specific about what they want. That is a strong market for an owner who can show a buyer what they are looking for.

92

HVAC services transactions from January 1 to July 27, 2026.

Capstone Partners, HVAC Services M&A Update, July 20261

47
backed by private equity, as add-ons or new platforms1
45
made by strategic buyers, 34 of them privately held1
63.8%
of HVAC technician demand met by available supply in 20242
85%
HFC phasedown required by 2036 under the AIM Act1
How a buyer reads an HVAC company

Five things are underwritten before price is discussed.

Each is a discount by default, and a point of value once it is evidenced.

01

The maintenance agreement base

This is the asset.

A buyer starts with the agreements: how many, what they pay, how many renew, and how much of your service and replacement revenue comes from agreement customers. A strong base turns a seasonal business into a recurring one, and the buyer pays for that.

What a buyer will ask to seeAn agreement roster tied to invoices and completed visits, renewal rates by year, and the share of replacements sold to existing agreement customers.
02

Service, replacement and construction

The mix tells the buyer how durable the revenue is.

Residential service and replacement driven by your own customer base reads as durable. New-construction work tied to a few builders reads as cyclical and concentrated. A record summer is welcome, and a buyer will normalize it.

What a buyer will ask to seeRevenue split by line of business for three years, gross margin by line, and customer concentration in construction work.
03

The technician bench

A buyer models what it costs to keep the team.

Supply met only 63.8% of HVAC technician demand in 2024. Every buyer knows this, so they look hard at headcount, tenure, certifications, pay plans and how you recruit and train. A bench that can absorb the loss of a lead tech is worth real money.

What a buyer will ask to seeTechnician roster with tenure and EPA Section 608 certifications, turnover history, compensation plans, and the training or apprenticeship pipeline.
04

Licenses, manufacturer relationships and the founder

What travels with you is priced as risk.

If the contractor license, the key distributor and manufacturer relationships, or the biggest commercial accounts run through you personally, the buyer prices the transition or structures around it with an earnout or a longer stay.

What a buyer will ask to seeA license succession path, written relationships at the company level, and key accounts already managed by someone other than you.
05

Commercial service contracts

Multi-year terms read as recurring revenue.

Commercial maintenance and service contracts with defined terms, renewal history and a spread of customers add a layer of recurring revenue that buyers underwrite with confidence.

What a buyer will ask to seeContract terms, renewal dates and revenue by customer, with no single customer dominating the book.
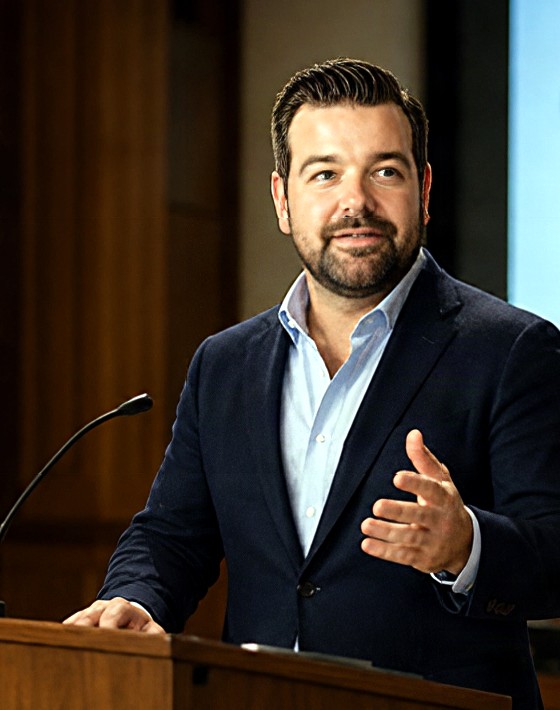
Ron Smith, Founding Partner, Cordis Global
On the work
The gap between what a founder builds and what they walk away with is the most preventable failure in this market. The information that closes that gap is knowable. It just doesn't reach the founder in a form they can act on. The work is making sure it does.
Ron Smith, Founding Partner, Cordis Global. Ron grew up in his family's HVAC business.
Head of Research, Cordis Institute · Author of Buyer-Ready
The part most owners find out too late

In HVAC, the first thing a buyer prices is who answers the phone in July.

The heat wave, the after-hours call, the commercial account that only trusts you. Each one tells a buyer how much of the company leaves with its founder.

Where it surfaces

Where HVAC deals lose value after the handshake.

01
The agreements nobody can tie out
A roster that does not match invoices and completed visits is read as one-time revenue, and priced that way.
02
The hot summer in the trailing twelve months
Record replacement revenue is welcome. The quality of earnings team will normalize it, and the price is set on the normalized number.
03
The lead tech, approached after the LOI
Recruiters and competitors notice when a company is in play. Retention that is not in writing becomes an escrow or an earnout.
04
The license and dealer status in your name
If the right to operate or a key manufacturer relationship needs your signature, the buyer structures the deal around it.
05
The add-back without a paper trail
Trucks, phones, family payroll and personal expense. If the document is not filed beside the adjustment, it comes back out of earnings.

Each one is fixable, and every one is cheaper to fix before a buyer finds it.

Who is buying

Six kinds of buyers read an HVAC company six different ways.

An add-on wants your agreements and your route. A platform sponsor wants your managers. A family office wants continuity. Knowing which one fits you is the first decision.

01

Private equity add-on

Prices within its lender's limits

Folds your agreements, technicians and territory into a platform it already owns, inside a senior-debt constraint that caps what it can offer.

02

Private equity platform

Prices the team, not the founder

Builds a regional HVAC company around yours. Needs a general manager, a service manager and systems that run without you.

03

Strategic acquirer

Prices to realistic synergy

A larger privately held HVAC or mechanical operator. Pays for territory, technicians and customers, and for the savings it can actually capture.

04

Public company

Prices to earnings and fit

A listed distributor, manufacturer or services group. Public buyers made 11 HVAC services acquisitions this year through July 27, up from 5 a year earlier. Pays for scale and audit-ready numbers.

05

Family office

Prices continuity and structure

Long hold, steady cash flow, a team that stays. Often keeps the name on the trucks and values a clean tax structure.

06

Search fund or independent sponsor

Prices to SBA lending rules

An operator who will run the company. Applies specific add-back rules and often values a longer transition with you.

Buyer archetypes adapted from The Buyer Lane Preparation Map, Cordis Institute. The Cordis MRI runs your own financials through each lane before you choose one.

The sequence

The work that moves the number, in the order it pays.

Most of it is done well before a buyer is in the room. The earlier it starts, the more of it becomes value instead of a discount.

Two to three years out

Document the agreements

Tie every maintenance agreement to invoices and visits. Track renewals by year. Report the share of replacements sold to agreement customers.

Eighteen months out

Build the bench below you

A service manager who runs dispatch and quoting. Retention plans for lead technicians. Licenses and key relationships held at the company level.

Twelve months out

Make the earnings hold

Evidence every add-back. Separate personal expense. Normalize the best year before a buyer does, so the number you show is the number that survives.

Six months out

Choose the lane

Run the company through each buyer lane, decide which one fits your goals, and prepare the materials that buyer will read first.

Confidential from the first word

No one hears about this conversation unless you decide they should.

Owners hesitate to make this call for one reason: what happens if the team, a customer or a competitor finds out. So the rule is simple, and it holds from the first email.

  • Your employees, customers, lenders and competitors hear nothing from us without your say-so.
  • Everything you share stays with the partner you share it with.
  • A first conversation requires no engagement, no NDA and no fee.
  • If a process begins, you decide which buyers see the company, and when any of them learn its name.
What the first conversation looks like
  1. 01
    A partner reads your note.It goes straight to a named partner, the same person who would carry the work.
  2. 02
    You hear back within one business day.A direct reply, and thirty minutes on the phone if talking would help. We ask about the business, your timeline and what matters to you beyond the number.
  3. 03
    You get an honest recommendation.A Value Protection Study, a mandate, or the name of somebody better suited. The study is fifteen written pages in five business days, with no fee and nothing to sign.
Start a confidential conversation
For CPAs, wealth advisors and estate attorneys

Your client's number is set long before the first buyer call.

You see the return, the entity structure and the estate plan. We see how a buyer will read the same company. A Value Protection Study gives your client a buyer's view of the business while there is still time to act on it, and keeps you at the center of the plan.

Forward this page to a clientIntroduce a clientForwarding opens a short, ready-to-send note in your own email. Nothing comes to us until you or your client reach out.
Questions owners ask first

Selling an HVAC company, answered plainly.

How much is my HVAC business worth?

A range, and where you land in it depends on which buyer is reading the company. The biggest drivers are the size and renewal rate of your maintenance agreement base, the mix of service and replacement against new construction, the depth of your technician bench, and how much of the business still runs through you. The Cordis MRI runs your own financials through each buyer lane and returns that range.

Who buys HVAC companies?

Private equity add-ons and platforms, privately held regional operators, public companies, family offices, and search funds or independent sponsors. Of the 92 HVAC services transactions recorded through July 27, 2026, 47 were sponsor-backed and 45 were made by strategic buyers, 11 of them public companies.

Do maintenance agreements increase the value of an HVAC company?

They are usually the single most important asset in the company, provided a buyer can verify them. Agreements tied to invoices, completed visits and renewals read as recurring revenue. Agreements that are sold but never serviced, or never renewed, read as one-time revenue.

What do buyers look for in an HVAC company?

Recurring revenue from maintenance agreements and commercial service contracts, replacement work that comes from your own customer base, a technician bench that can absorb turnover, licenses and manufacturer relationships that transfer, and earnings that hold up when the buyer's accountants test them.

Should I sell my HVAC company to private equity or a competitor?

It depends on what you want beyond the number. A private equity add-on, a regional strategic, a public company, a family office and a search fund each price the same company differently and treat your name, your team and your role after closing differently. Choosing the lane before going to market is one of the highest-value decisions in the process.

Will my technicians stay after the sale?

Retention is something a buyer will price, so it is best addressed before the sale. Clear leadership below you, documented compensation plans and retention agreements for key technicians, put in place ahead of a process, protect both your team and your price.

How long does it take to sell an HVAC business?

A market process commonly runs six to nine months from launch to close. Preparation is the variable that matters: the strongest outcomes usually follow one to three years of work on agreements, the bench and the earnings.

Does the refrigerant transition affect a sale?

Buyers will ask about it. The AIM Act phases down HFC production and consumption by 85% by 2036, which shapes replacement demand and the training your technicians need. A clear answer on certification and on how your company is handling the transition reads as strength in diligence.
Other trades

A confidential conversation is where it starts.

One call about your company and your timeline. You decide what happens next.

HVAC coverageContact Cordis Global
Office420 Lexington Avenue, Suite 300
New York, NY 10170
Sources · data as of July 27, 2026
  1. Capstone Partners, HVAC Services M&A Update, July 2026. Figures are year to date through July 27, 2026, and include the AIM Act phasedown figure.
  2. TechForce Foundation, as cited in Capstone Partners, Residential Services Sector Update, October 2026.
  3. Ron Smith, Q&A, cordisglobal.com/ron-smith.